
Common Mistakes When Structuring Foreign Investments in Dakar and How to Avoid Them
Establishing a business presence in Dakar, Senegal, offers access to a rapidly growing West African market with significant potential for expansion. However, navigating the local regulatory landscape requires precise structural planning to ensure compliance and maximize operational efficiency. Recent economic analyses indicate that foreign direct investment in West Africa has seen a steady upward trend, yet many enterprises fail to capitalize on this growth due to avoidable legal and financial errors. Understanding the specific requirements of the OHADA legal framework and local tax codes is essential for any investor looking to establish a sustainable foothold in the region.
Understanding the OHADA Legal Framework
Senegal operates under the Organization for the Harmonization of Business Law in Africa, commonly known as OHADA. This supranational legal system harmonizes business laws across its member states, including Senegal, to create a more predictable environment for commerce. OHADA is a legal framework designed to unify business laws across West and Central Africa. For foreign investors, this means that corporate governance, commercial contracts, and dispute resolution mechanisms follow standardized rules rather than disparate local customs.
One of the most frequent errors investors make is ignoring the specific procedural requirements mandated by OHADA treaties. These requirements often dictate how corporate bylaws must be drafted and how shareholder meetings are conducted. Failure to adhere to these standards can render corporate decisions void or subject to legal challenge. Investors must ensure that their corporate structure is registered with the Centre Régional de Commerce et de Crédit Immobilier (CRCI) in Dakar to be recognized as valid.
Another critical aspect is the enforcement of contracts. Under OHADA, the Uniform Act on Arbitration provides a robust mechanism for resolving commercial disputes. However, this mechanism is only effective if the arbitration clause is correctly drafted in the initial agreements. Many foreign companies draft contracts using common law principles, which can lead to significant enforcement issues in Senegalese courts. It is vital to align all contractual language with the Uniform Acts governing commercial obligations and general civil procedure.
Choosing the Right Business Entity
Selecting the appropriate legal structure is the foundational step in any investment strategy. In Senegal, the most common vehicle for foreign investment is the Société à Responsabilité Limitée (SARL) or the Société Anonyme (SA). A SARL is a limited liability company suitable for small to medium-sized enterprises. It offers flexibility in management and is generally easier to establish than a public limited company.
The SARL structure requires a minimum of two shareholders and allows for a more informal management style compared to the SA. This makes it ideal for joint ventures or smaller foreign subsidiaries. However, the SA is required for larger operations, particularly those seeking to raise capital from the public market or listed on the Bourse Régionale des Valeurs Mobilières (BRVM). The SA demands a minimum capital of 10 million CFA francs and a more rigid corporate governance structure.
A common mistake is underestimating the administrative burden of the SA structure for a small-scale operation. Investors often choose the SA for prestige or perceived legitimacy, only to find the compliance costs prohibitive. Conversely, some investors attempt to operate as a sole proprietorship to save on setup costs, which exposes personal assets to business liabilities. Understanding the liability implications of each structure is crucial for risk management.
Tax Compliance and Fiscal Pitfalls
Senegal has a complex tax regime that includes corporate income tax, value-added tax (VAT), and various social security contributions. The standard corporate income tax rate is 30 percent, but incentives are available for investments in specific sectors or regions. VAT is a consumption tax levied on goods and services within the jurisdiction. The standard rate is 18 percent, with reduced rates for essential goods and services.
One significant pitfall is the misclassification of employee benefits and social security contributions. Senegal has strict labor laws that mandate specific contributions to the CNPS (Caisse Nationale de Prévoyance Sociale). Failure to accurately calculate and remit these contributions can result in heavy penalties and interest charges. Investors must also be aware of the withholding tax requirements on payments made to non-resident entities, such as royalties, dividends, and interest.
Another area of concern is the transfer pricing regulations. Senegal aligns its transfer pricing rules with OECD standards, requiring related-party transactions to be conducted at arm's length. Companies that fail to maintain proper documentation for intercompany transactions risk audits and adjustments by the Direction Générale des Impôts et des Domaines (DGID). Establishing a robust transfer pricing policy from day one is essential to avoid future disputes and financial losses.
Capital Requirements and Repatriation
Foreign investors must navigate the foreign exchange regulations set by the Central Bank of West African States (BCEAO). While the CFA franc is pegged to the Euro, ensuring the smooth repatriation of profits is a key concern for many investors. Repatriation of profits is the process of transferring earnings back to the investor's home country. Senegal generally allows for the free transfer of capital and profits, provided that all tax obligations are met.
A common mistake is failing to register the investment with the Direction de la Monnaie et du Crédit (DMC) upon arrival of funds. This registration is necessary to obtain the attestation required for future repatriation of dividends or capital. Without this documentation, investors may face significant delays or restrictions when trying to move money out of the country. It is also important to understand the minimum capital requirements for different business types, which can vary based on the sector of operation.
Additionally, investors should be aware of the potential for currency fluctuation risks, even with the peg. While the peg provides stability against the Euro, it may not protect against fluctuations against other major currencies like the US Dollar. Hedging strategies should be considered for large-scale investments to mitigate financial exposure. Working with local banks that specialize in international trade finance can provide valuable insights and tools for managing these risks.
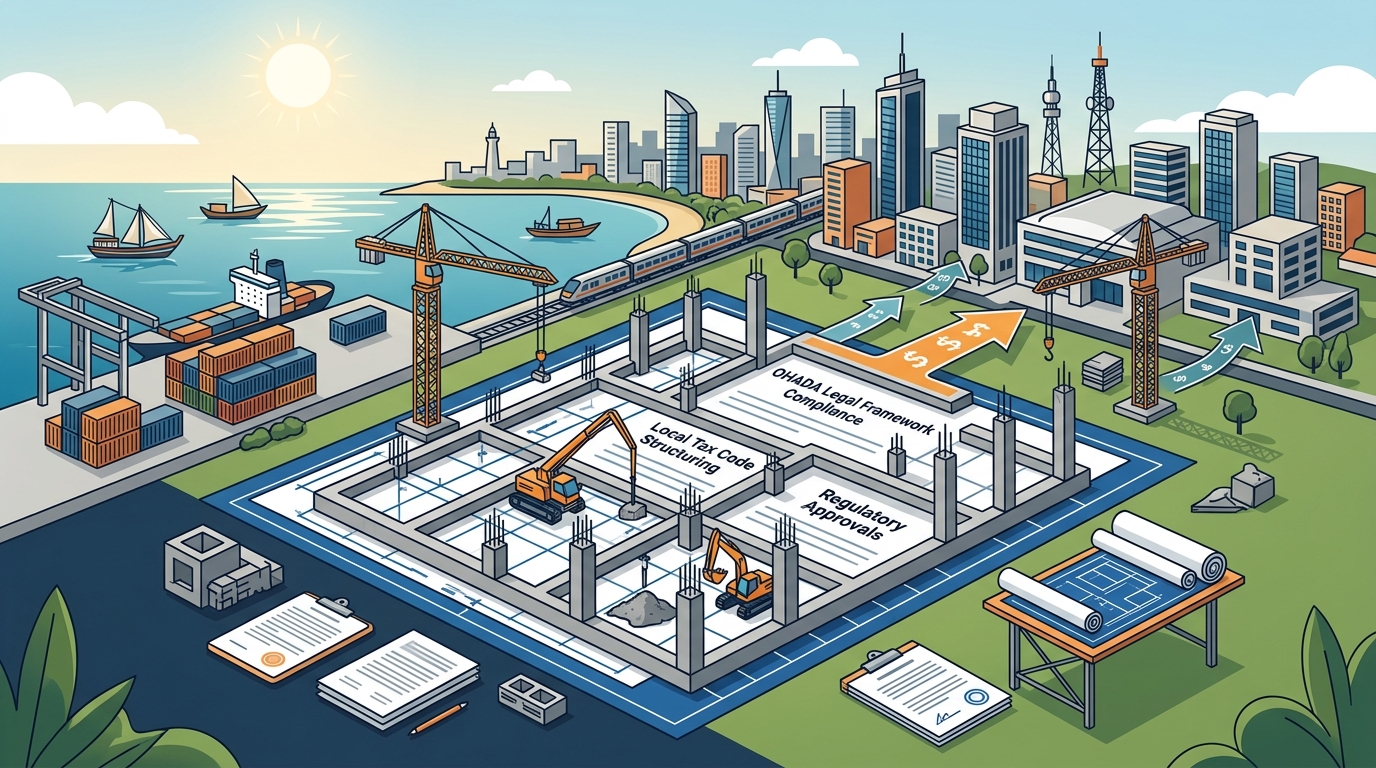
Navigating Local Partnerships
Partnering with local entities can provide valuable market access and regulatory navigation support. However, choosing the wrong partner can lead to operational conflicts and legal disputes. Due diligence is critical when selecting a local partner. This includes verifying their financial stability, reputation, and compliance history. Due diligence is the comprehensive investigation of a potential business partner. It helps identify any hidden liabilities or risks before finalizing the agreement.
Another common error is failing to clearly define the roles and responsibilities in the partnership agreement. Ambiguity in decision-making authority can lead to deadlocks and operational inefficiencies. It is essential to establish clear governance structures, including voting rights and dispute resolution mechanisms. Intellectual property rights should also be explicitly addressed to protect proprietary technologies and brand assets.
Furthermore, cultural differences can impact business operations. Understanding the local business culture and communication styles is vital for building strong relationships. Investing time in building trust with local stakeholders can facilitate smoother negotiations and regulatory approvals. Engaging local legal and financial advisors early in the process can help bridge cultural gaps and ensure that the partnership is structured for long-term success.
Comparing Investment Structures
To assist in decision-making, it is helpful to compare the primary investment structures available in Senegal. The following table outlines the key differences between the SARL and SA structures, as well as the branch option.
| Feature | SARL (Limited Liability Company) | SA (Public Limited Company) | Branch Office |
|---|---|---|---|
| Minimum Capital | 10 million CFA francs | 10 million CFA francs | No minimum |
| Shareholders | 2 to 50 | 7 to infinity | 1 (Parent Company) |
| Management | Gérant(s) | Directoire and Conseil de Surveillance | Representative |
| Taxation | Corporate Income Tax | Corporate Income Tax | Corporate Income Tax |
| Complexity | Low to Medium | High | Medium |
Choosing the right structure depends on the scale of operations, funding needs, and long-term strategic goals. For most small to medium foreign investors, the SARL offers the best balance of flexibility and liability protection. Larger enterprises or those planning to go public may find the SA structure more appropriate. Branch offices are suitable for companies testing the market without establishing a separate legal entity.
Key Takeaways
- Senegal is part of the OHADA legal system, which standardizes business laws across member states.
- The SARL is the most common structure for foreign investors, requiring a minimum capital of 10 million CFA francs.
- Corporate income tax in Senegal is generally 30 percent, with specific incentives for certain sectors.
- Registration with the DMC is mandatory for the repatriation of profits and capital.
- Transfer pricing documentation must comply with OECD standards to avoid audits.
- Local partnerships require thorough due diligence to mitigate operational and legal risks.
- Understanding the distinction between SARL and SA structures is critical for compliance and governance.
Frequently Asked Questions
What is the minimum capital required to start a business in Dakar?
The minimum capital for a SARL is 10 million CFA francs. For an SA, the minimum is also 10 million CFA francs, but it requires a minimum of seven shareholders.
How long does it take to register a company in Senegal?
Registration typically takes between two to four weeks, depending on the complexity of the structure and the efficiency of the local CRCI office.
Can foreign investors repatriate profits freely?
Yes, profits can be repatriated freely provided that the investment is registered with the DMC and all tax obligations are fulfilled.
What is the standard VAT rate in Senegal?
The standard VAT rate is 18 percent, with reduced rates applying to certain essential goods and services.
Is a local partner required for foreign investment?
No, foreign investors can own 100 percent of a SARL or SA. However, having a local partner can provide valuable market insights and regulatory support.
What are the main tax incentives for foreign investors?
Incentives may include tax holidays, reduced corporate tax rates, and exemptions on import duties for equipment, depending on the sector and location of the investment.
How are labor laws enforced in Dakar?
Labor laws are strictly enforced, with mandatory contributions to the CNPS and specific requirements for employment contracts and working hours.
What is the role of the BCEAO in foreign investment?
The BCEAO regulates monetary policy and foreign exchange controls, ensuring the stability of the CFA franc and facilitating international transactions.
Contact Our Experts
Navigating the complexities of foreign investment in Dakar requires expert guidance to ensure compliance and maximize your returns. At SunuLex, we specialize in providing comprehensive legal and financial advisory services for international investors entering the West African market. Our team of experts is dedicated to helping you structure your investment efficiently and avoid common pitfalls. Contact SunuLex today to schedule a consultation and secure your future in Dakar.